India’s clean energy ambitions now extend well beyond installing renewable generation capacity towards increasingly making clean energy technologies in India, competitively and at scale. Public research, development, and demonstration (RD&D) builds a country’s knowledge of production processes, materials, systems integration and scale-up, and it is where industrial ambition can translate into domestic capability. This study sets out to answer whether India’s public RD&D is building the knowledge and capabilities its clean energy and industrial ambitions require.
Until now, this system has been hard to see as a whole. Funding is spread across multiple ministries and agencies, with no central register that consolidates them into a view of the public research base. Our report brings together 1,359 publicly funded projects at 90+ institutions, active between 2019 and 2024, representing about INR 1,443 crore (USD 151 million) in declared funding. It covers six areas: renewables, power and storage, hydrogen and fuel cells, transport and e-mobility, energy efficiency, and carbon capture, utilisation and storage.
Concurrently, our new India Clean Energy RD&D Tracker provides a breakdown of publicly available clean energy investments and activities across technologies, institutions, and types of innovation.
We examine how research effort is distributed across technologies, what kinds of innovation the portfolio supports, whether the focus is on products or production processes, and whether all this aligns with India’s broader clean energy, industrial, and climate objectives. The dataset is assembled from publicly available disclosures and should be understood as an evolving resource rather than a complete census of India’s public clean energy RD&D.
What India’s clean energy RD&D portfolio contains
Effort is concentrated, more so by funding than by project count. Among the mapped projects, renewables account for 421 projects and INR 580 crore (USD 61 million), followed by power and storage at 333 projects and INR 492 crore (USD 52 million). Together they absorb about three-quarters of declared spending. Within renewables, solar photovoltaics alone take 234 projects and INR 401 crore (USD 42 million), more than the hydrogen, energy efficiency, transport, and CCUS categories combined.
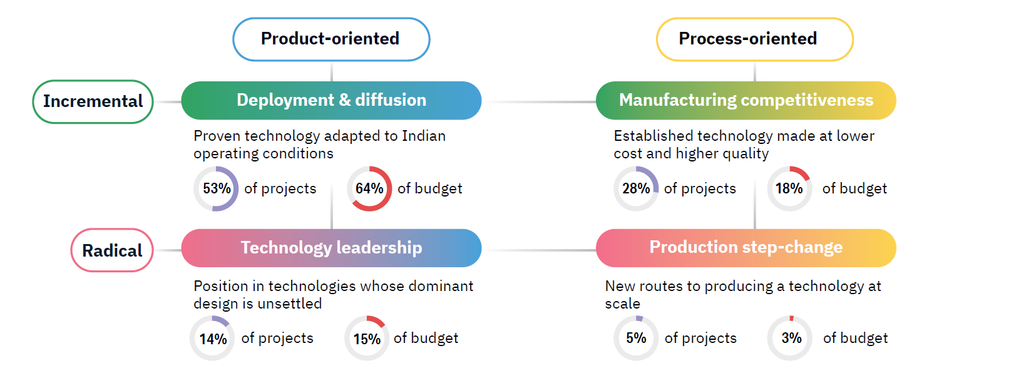
The research is overwhelmingly incremental and product-focused. Across the mapped projects, 81% improve, adapt, or optimise technologies already in commercial use, while 67% focus on products. This pattern is consistent across renewables, storage, and hydrogen.
Funding is fragmented, while projects are small and uniform in scale across technology categories. Across the portfolio, 68% of projects with declared budgets receive less than INR 50 lakh (USD 52,000) and median project size varies only between INR 33 lakh and INR 39 lakh (USD 35,000–41,000) across technology categories, suggesting that different types of research are often supported through similar funding instruments.
Why this matters
India’s transition is occurring under conditions that imported technologies do not automatically accommodate. Research focused on adapting technologies to local conditions can generate real near-term returns. Viewed through that lens, the portfolio is well aligned with India’s deployment needs.
Deployment, however, is no longer India’s only objective. Manufacturing capability has become an explicit national priority. Product innovation determines what is made; process innovation determines how it is produced efficiently, consistently, and at competitive cost. Yet the mapped public RD&D portfolio remains weighted heavily towards product innovation.
The funding architecture reinforces this pattern. Uniform grant sizes may be appropriate for investigator-led research but are less well suited to pilot manufacturing, production engineering, demonstration, and scale-up, where manufacturing capabilities are often developed. Different capability objectives therefore appear to require different funding instruments.
Where public RD&D effort sits: projects and budget by strategic objective Source: Authors classification and analysis
The central finding is that the balance between deployment, manufacturing capability, and technology leadership appears to have emerged from many independent funding decisions, without an explicit portfolio-level strategy visible in the public record.
What follows
State the intended balance. RD&D strategies should articulate capability objectives alongside technology priorities, making explicit what public investment is expected to contribute to deployment, manufacturing competitiveness, and technology leadership.
Monitor the portfolio, not only the individual project. Portfolio-level monitoring should complement project-level evaluation, allowing policymakers and funders to assess whether aggregate investment remains aligned with evolving national objectives.
Differentiate funding instruments. Different stages of innovation require different scales, time horizons, and institutional arrangements. Broadening the mix of funding instruments is likely to address important gaps more directly than increasing the overall budget alone.
Treat process innovation as a strategic objective in its own right. Work on production methods, manufacturing equipment, quality control, and pilot-scale validation sits closer to industrial production than conventional laboratory research. Supporting these capabilities is likely to require stronger collaboration between public research institutions and industry.
The shift to EVs is happening worldwide; about one in four cars sold in 2025 was electric (International Energy Agency 2026). Over the last decade, India has begun a serious push toward electric vehicles (EVs). The Government of India and most state governments have implemented a range of demand and supply-side support policies (Government of India, n.d.-c, n.d.-d), and the early momentum has come from below. Start-ups and established automakers have begun to make real gains, primarily driven by the rapid adoption of electric two- and three-wheelers (e2W and e3W) (Government of India, n.d.-b; EVreporter.com 2026).
In parallel, public charging has begun to expand in major cities and along key highways (Government of India, n.d.-a) and domestically assembled models are now on sale across a range of prices.
The numbers capture how quickly this has moved: between FY 2019-20 and FY 2024-25, annual EV registrations rose from 1.74 lakh to 19.68 lakh, an increase of elevenfold even after a pandemic dip (PIB Delhi 2026b).
Yet the transition is far from settled. EVs still cost more than their internal combustion engine vehicle (ICEV) equivalents, which keeps a capable EV beyond the reach of much of the mass market (Elango et al. 2025; Ministry of Power 2023). The stakes are only growing, with India’s vehicle population projected to more than double by 2050 (Mohan et al. 2025), and a fleet that still runs on fossil fuels would lock in high and continuing costs from greenhouse gas and air-pollutant emissions (International Energy Agency 2023). The fuel supply shock that has followed the closure of the Strait of Hormuz in early 2026 has further sharpened the case for EVs (Shyamasis Das 2026).
The industrial stakes are just as high. India is the world’s fourth-largest automaker, and vehicle manufacturing accounts for roughly half of its manufacturing GDP (NITI Aayog 2025a). The ICEV industry rests on two pillars: large manufacturers and a base of more than 35,000 component makers, most of whom are small and medium-sized firms (Gupta et al. 2023). EV manufacturing has not yet reached the same maturity, and India risks falling behind its competitors. Because China dominates EV manufacturing, there is a particular worry lurking beneath the transition: India could trade its dependence on imported fossil fuels for a new dependence on imported EVs and their components (PIB Delhi 2026a).
However, the same moment also presents an opportunity to build a competitive EV manufacturing industry, one that increases industrial employment and exports while avoiding new import dependence. Past industrial policy helped India catch up in conventional vehicles and build a strong automotive base, even if that base has struggled to produce globally competitive cars (United Nations Industrial Development Organization and Department of Science and Technology 2023).
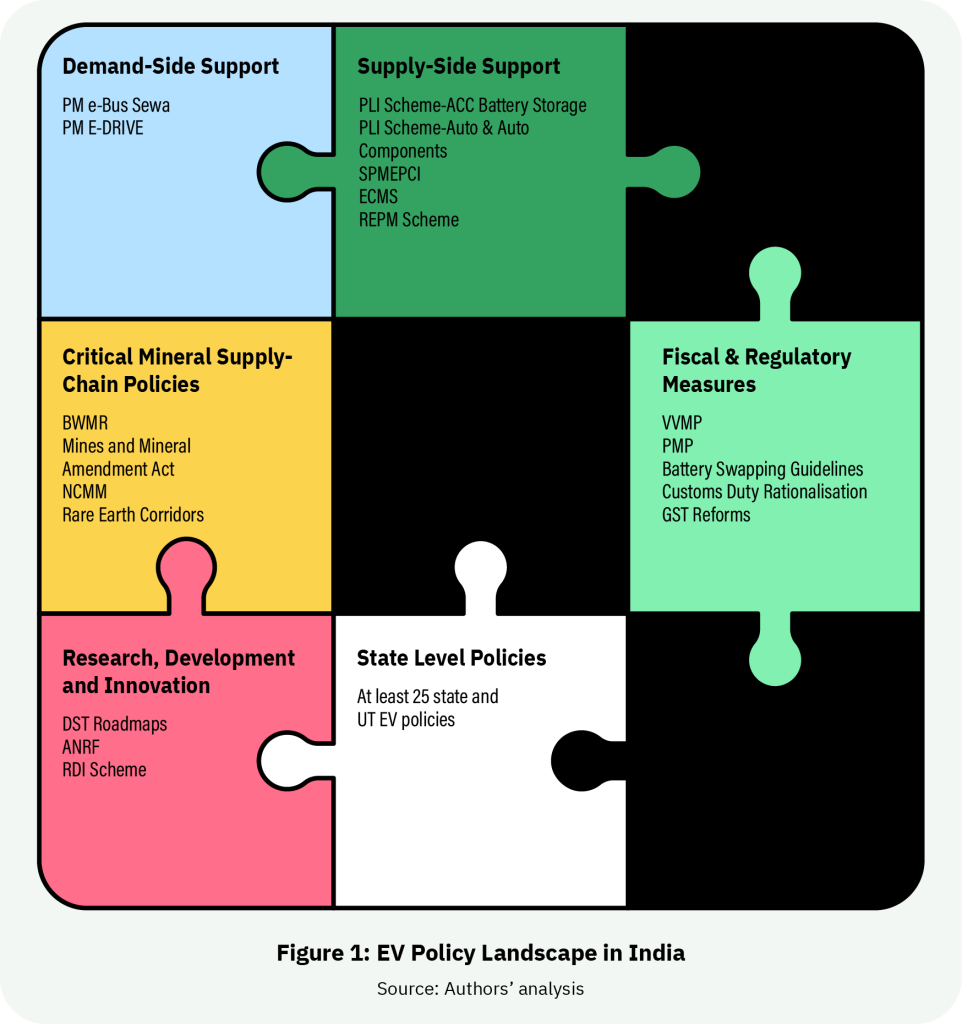
The strategic questions, therefore, remain. Can India strengthen its automobile sector in the EV era? What would success in EV manufacturing look like? What obstacles lie in the way? Moreover, does India’s current research, development and demonstration (RD&D) ecosystem possess the capabilities required to support that ambition? Our issue brief examines these questions by analysing the evolution of India’s EV policy landscape, the current state of domestic manufacturing, and the strengths and limitations of its RD&D ecosystem.
India has recently approved its second Nationally Determined Contribution (NDC) to the Paris Agreement, for the period 2031-35. This commitment, despite being announced nearly five months late, serves as an important signal of India’s intent to decarbonise and support global efforts to limit climate change. It also constitutes a critical pillar of the Agreement’s ratchet mechanism, designed to progressively scale up global climate action in a manner that is compatible with the principle of Common but Differentiated Responsibilities and Respective Capacities (CBDR-RC).
India’s original NDC in 2016 had been welcomed as representing significant climate action from a country that accounts for under 4% of historical emissions and whose per capita emissions are still under half the global average. It had three quantified targets and has easily surpassed the first two, enabling it to further tighten its subsequent targets. The original targets and their revisions are shown in Table 1 below.
Table 1: India’s NDC targets. Source: Authors’ compilation based on India’s NDC commitment announcements.
Of these, the emissions intensity (EI) target is the only economywide measure of climate progress, and it encompasses all other decarbonisation actions, including those relating to its other NDC targets for increasing non-fossil-based electricity capacity and carbon sinks. This EI target is our focus in this article, to better contextualise it and understand the scale of ambition it represents.
Alignment with India’s emissions intensity trajectory
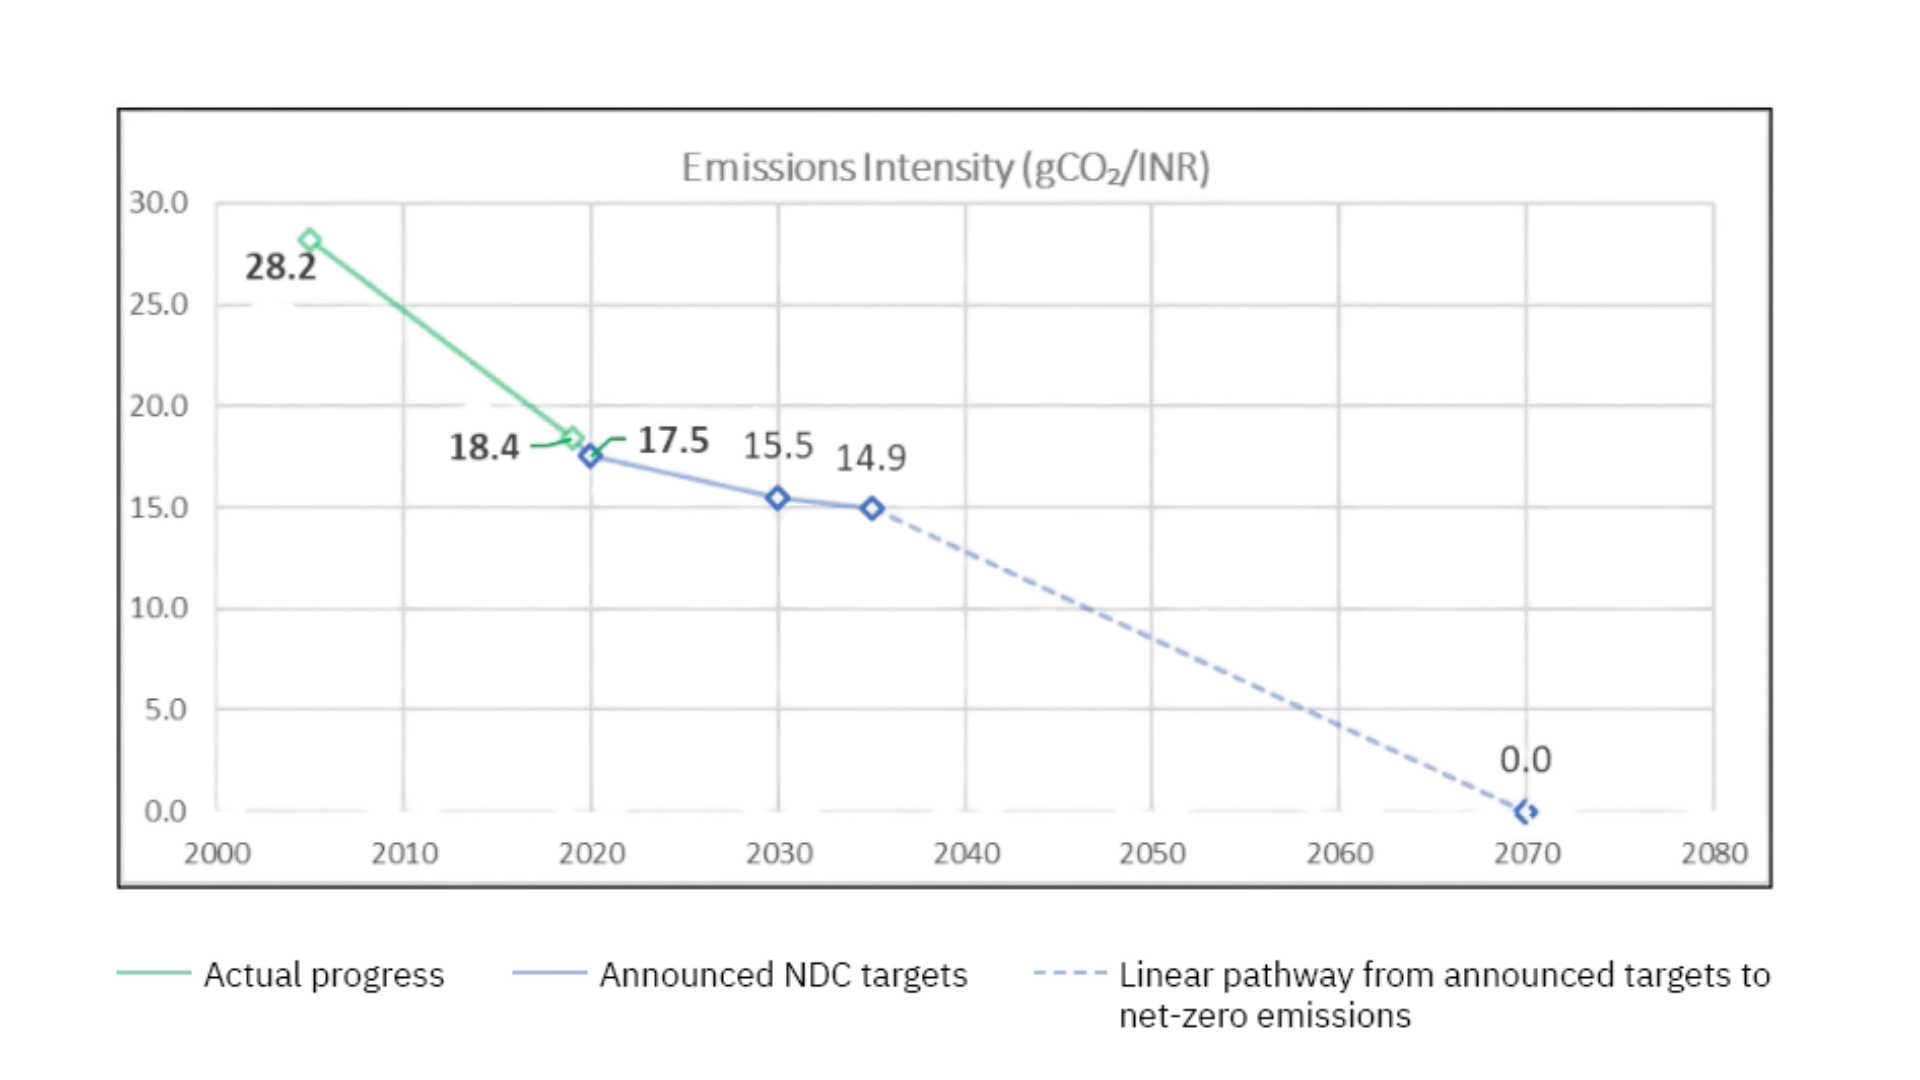
With India’s 2005 emissions estimated to be 1.64 GtCO2e1 and GDP at INR 58.1 trillion2, its 2005 EI was approximately 28.2 grams of CO2 equivalent (gCO2e)/rupee. Using the latest official emissions data from India’s Biennial Update Report to the UNFCCC and GDP data from MOSPI, we calculate India’s actual emissions intensity in 2019 and 2020 (see Figure 1), and observe that emissions intensity had already fallen by nearly 38% below 2005 levels by 2020, ten years ahead of its INDC commitment.
Figure 1: Emissions intensity has steadily declined since 2005 and is projected to continue falling, but reaching net-zero intensity by 2070 requires a sharp acceleration beyond current trends. Source: Authors’ analysis.
As such, the updated NDC target of 2022 required only an additional 7% reduction in emissions intensity over 10 years, and the second NDC an even more modest 2% reduction over the next five. If India has linearly continued its 2005-2020 rate of EI reductions past 2020 – an admittedly simplistic and challenging assumption – it will already have reached its 47% target by 2024.
Alignment with Modelled Projections
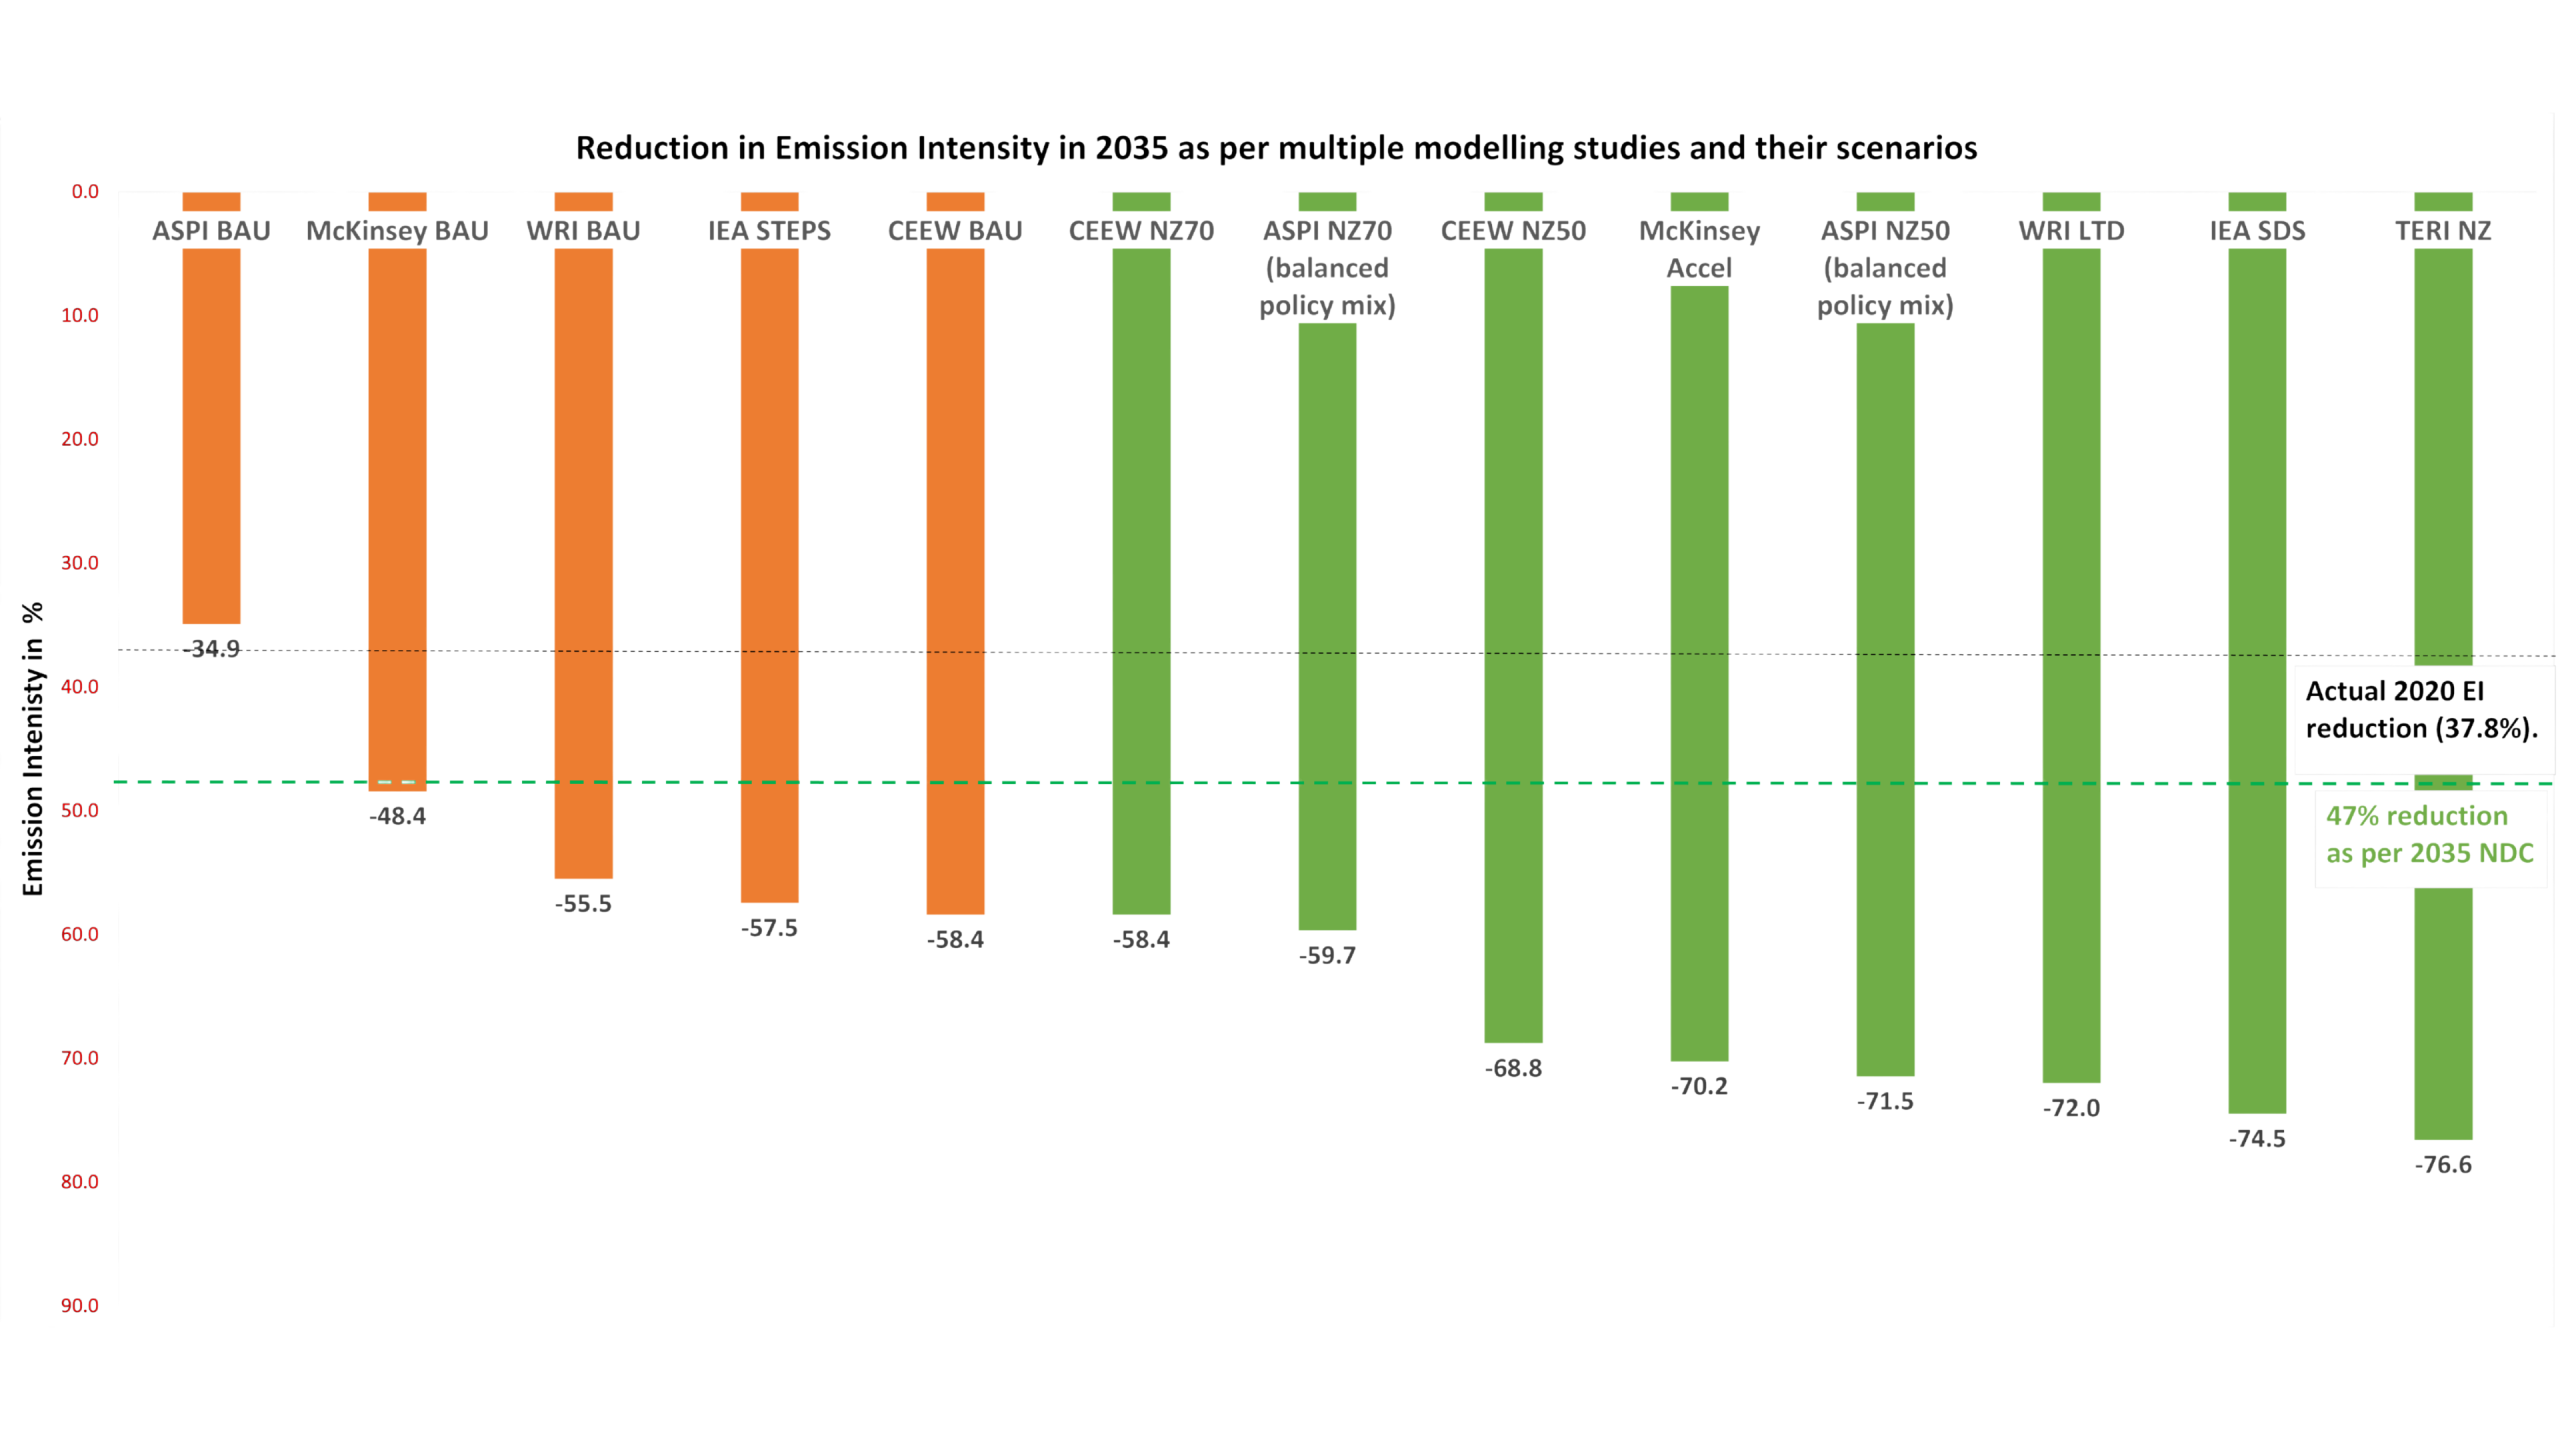
An assessment of 13 projected scenarios from five emissions-economy modelling studies that have explored India’s growth and emissions pathways3 further contextualises the recent pledge (Figure 2). Five of these projections (represented by the orange bars) can be interpreted as ‘reference’ scenarios, as they represent a continuation of trajectories that incorporate only existing decarbonisation policies and targets as of 2018-2020. The remaining eight are designed to represent scenarios based on additional policies that suggest possible pathways towards full decarbonisation in the second half of the century. The 47% intensity pledge appears to be consistent with – or even less ambitious than – decarbonisation pathways reflected in four of the reference scenarios here.
Figure 2: Most modelled decarbonisation pathways exceed India’s 47% intensity-reduction pledge by 2035, indicating that current targets align with, or fall short of, even baseline policy scenarios. Source: Authors’ analysis. Notes: (i) TERI-Shell and IEA only model emissions from the energy sector. (ii) IEA provides GDP estimates at 2019 prices; TERI-Shell GDP is based on MoSPI estimates at FY2011-12 prices. (iii) IEA GDP is converted using the exchange rate in its Annex B. (iv) An inflation adjustment is applied from the base year to rescale IEA estimates to FY2011-12 prices, based on a Ministry of Finance Cost Inflation Index.
Impacts on the Carbon Budget
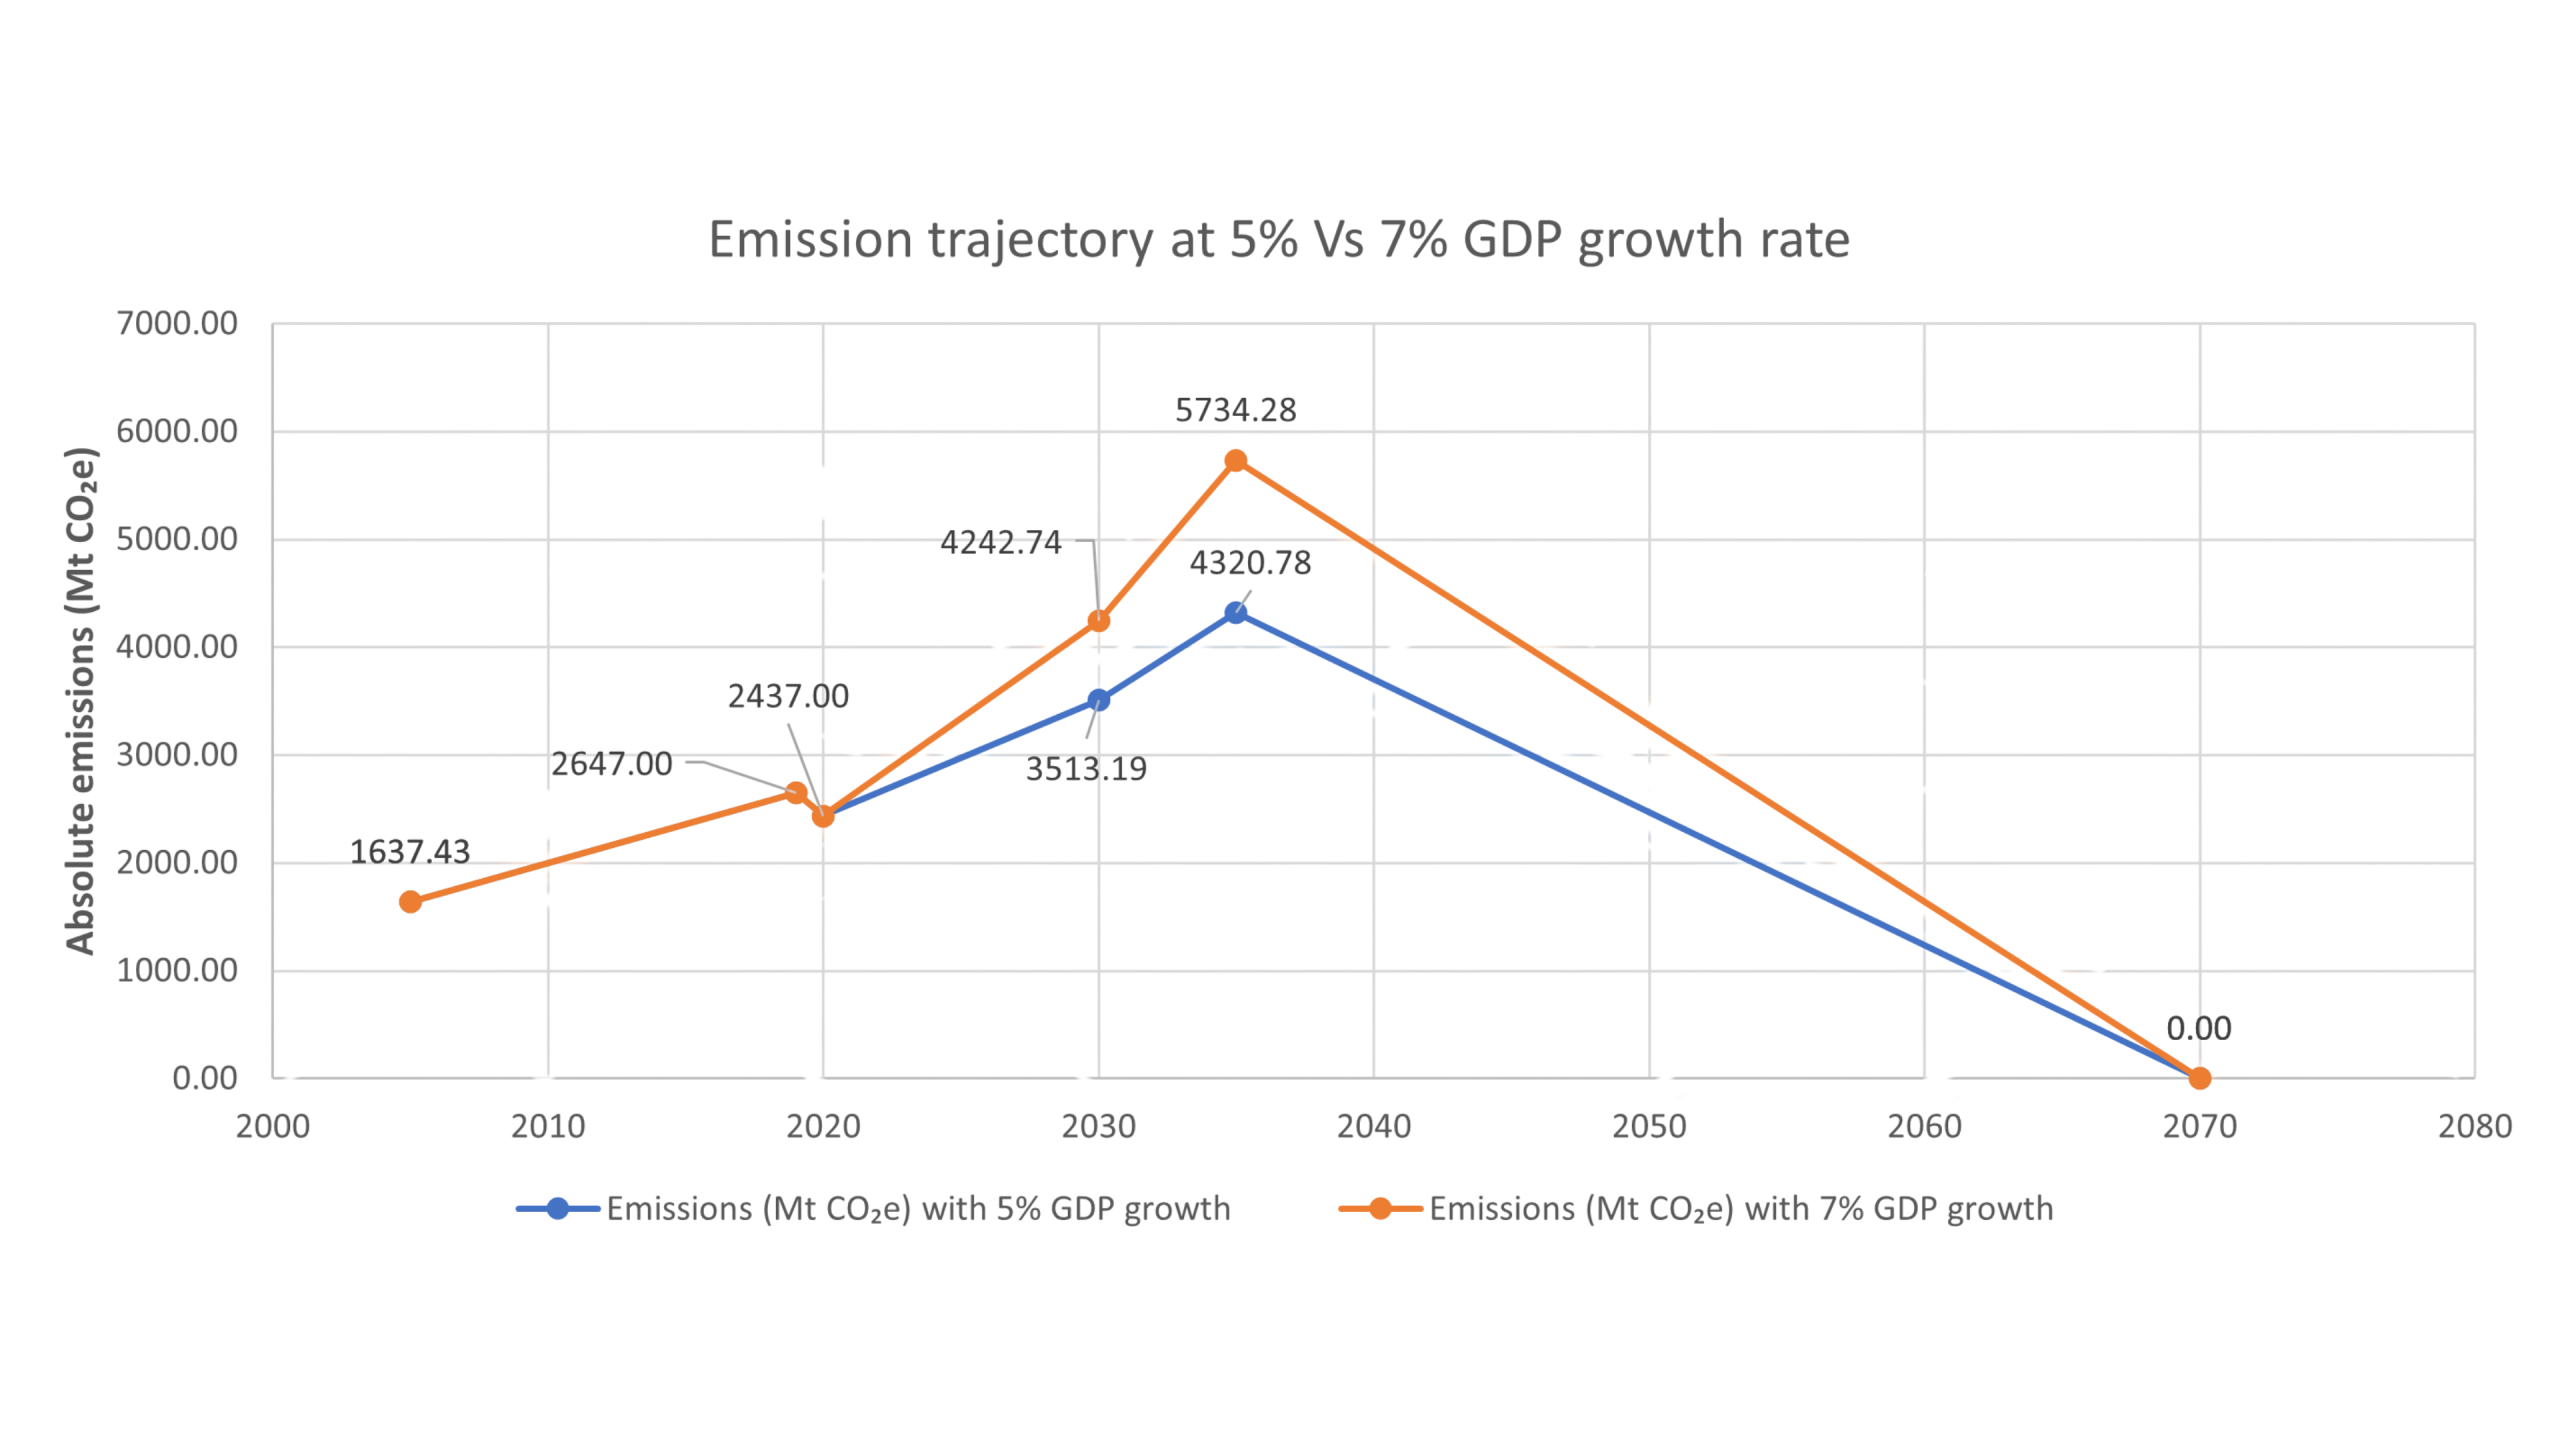
If India were to indeed limit its emissions intensity reductions to 47% by 2035, then – assuming an immediate and linear subsequent decline towards its 2070 net-zero target under constant 5% and 7% GDP growth rates – it would use up between 123 and 158 GtCO2e of the global carbon budget, respectively (Figure 3).
Figure 3: Higher growth raises the peak and delays the decline: emissions under 7% GDP growth peak ~1.4 GtCO₂e above the 5% pathway before both converge to net zero by 2070. Source: Authors’ analysis.
With a remaining global carbon budget of only 400 GtCO2e as of 2020 to stay within the 1.5°C limit, India could thus exhaust up to 30-40% of this amount alone, with the wiggle room it has created for itself.
Drivers and Implications
While our analysis of the 2022 targets notes that the intensity pledge may serve as an ex-post reflection upon the feasibility of a set of regularly enhanced climate policies, and may represent a conservative underestimate aimed at overachieving its targets, these comparisons suggest that India’s stated climate ambition for the 2030-2035 period is proportionally modest, and is significantly scaled back from earlier efforts.
This is particularly noteworthy given that India’s emissions grew only 0.7% in 2025, while its GDP growth for the same year was forecast at 7.3%, pointing to a single-year emissions-intensity reduction of 6.6% – meeting nearly the entirety of the distance to the updated 2030 target in a single year alone.
The modest ambition of this target may, in large parts, be a product of the moment. The United States’ withdrawal from the Paris Agreement and receding climate finance commitments from other developed economies have weakened faith in the multilateral climate architecture. Parallel unilateral measures such as the EU’s Carbon Border Adjustment Mechanism – widely viewed in the Global South as protectionist – have further eroded trust in the Global North. In this context, India’s willingness to raise its stated ambition at all is of diplomatic significance, signalling its continued commitment to the Paris framework even in the face of real or perceived inaction by others.
At the same time, it creates more wiggle room for India to scale back its climate actions, and, given its misalignment with India’s own net-zero commitment and its potentially significant impacts on the carbon budget, may be viewed with concern. The argument for more ambitious action has never been stronger. India ranks among the world’s most climate-vulnerable nations, with over 85% of its districts exposed to extreme climate events. Further, in an era of emerging deglobalisation and greater supply chain uncertainties, the strategic case for energy self-sufficiency – enabled by greater domestic clean tech innovation and manufacturing capabilities – has acquired salience that extends beyond climate considerations.
An emerging vacuum has created an opportunity for India to step more decisively into a leadership role in global climate diplomacy, in a manner that is consistent with its own needs. A more ambitious mid-term signal could have cemented that role; instead, the new target represents a missed strategic opportunity and has opened up space for criticism, not unlike the global response to COP26.
The key question now is whether stated ambition is at all the driver of climate action, and whether India’s implementation once again significantly outpaces its stated ambition.
Endnotes
Linearly interpolating between the 2000 and 2007 values ↩︎
Each study used different inputs and assumptions relating to data sources, currencies, exchange rates, growth rates, base years, and other parameters. Although we attempted to harmonise estimates to a common baseline, insufficient clarity on modelling processes may limit the direct comparability of these studies. ↩︎
Despite the need to limit climate change and transition to low-carbon energy, there is disagreement about how to share the burden of reducing CO2 emissions. Different approaches to global mitigation are assessed in this paper, accounting for three key factors: avoided climate harms, health (co)benefits from improved air quality, and the economic cost of CO2 policies. The approaches are then ranked according to different preferences for inter-generational and intra-generational equity.
Methods We compare a reference scenario to three scenarios that limit warming to 2°C: one through least cost, one that shifts mitigation burden towards higher-income countries (referred to as the international equity scenario), and a third that is identical to international equity, but within which low-income and middle-income countries (LMICs) also adopt air quality policies to reduce air pollution to the levels that occur in least-cost. Emissions and policy costs are modelled with Global Change Analysis Model, air quality with GEOS-Chem, health impacts with the Global Exposure Mortality Model, and climate benefits with Greenhouse Gas Impact Value Estimator.
Findings Climate action to limit global warming to 2°C results in more than 13·5 million avoided premature deaths from air pollution between 2020 and 2050, mostly in middle-income countries. Opting for the least-cost scenario rather than international equity reduces the mitigation burden for LMICs but also reduces their health co-benefits by several million deaths, highlighting a trade-off between mitigation effort (an important component of climate justice) and the urgent need to reduce environmental health burdens in LMICs. The extent to which equity is prioritised determines what to do about that trade-off; as more priority is given to lower-income countries, the international equity scenario is preferred. The most favourable scenario is the combined international equity and air quality scenario, whereby higher-income countries pay more climate mitigation costs, and LMICs use the cost savings to implement conventional air quality controls that offset foregone health co-benefits.
Interpretation Justice-centred climate mitigation strategies must ensure that LMICs do not miss an opportunity to realise transformative reductions in air pollution.
Energy storage has emerged as a cornerstone technology for clean energy transitions globally. As power systems incorporate higher shares of variable renewable energy, maintaining reliability requires the ability to balance supply and demand across time. In India, where the target is 500 GW of non-fossil electricity capacity by 2030, this balancing challenge is becoming increasingly central. India’s energy storage requirement is expected to rise five-fold, with some projections suggesting 411.4 GWh by 2031–32, underscoring the scale and pace at which storage technologies will need to be developed and deployed. To adequately support high renewable penetration, system adequacy, and grid stability, grid-scale storage power capacity could reach up to 178 GW by mid-century, according to net-zero-consistent power-system modelling.
Energy storage technologies differ not only in the medium used to store energy, but also in the time scales, services, and system roles they are designed to perform, as well as the required research, development and demonstration (RD&D) needs. For instance, electrochemical storage1 dominates short- to medium-duration (15 minutes to <8 hours) applications where fast response, modularity, and ease of deployment are critical. Meanwhile, mechanical2, thermal3, and chemical4 storage technologies tend to serve longer-duration (> 8hours to days) or system-level roles, such as bulk energy shifting, inertia provision, or seasonal balancing, but are often more site-specific and infrastructure-intensive. In parallel, enabling layers, including power electronics, control systems, and software, cut across storage technologies and play a critical role in determining how effectively storage assets interact with the grid. These technologies differ from most other clean energy technologies in three ways.
Firstly, storage technologies do not generate energy; they provide flexibility. Their value lies in services such as peak shaving, frequency regulation, voltage support, reserve provision, and congestion management. As a result, storage performance cannot be assessed independently of the power system in which it operates. This contrasts with solar or wind technologies, where performance improvements are largely intrinsic to the device.
Secondly, storage technologies operate across multiple time scales. Storage must respond in milliseconds to stabilise the grid, operate over a few hours to shift solar power to evening peaks, and potentially store energy for longer periods in the future, particularly to manage multi-day renewable variability or extended supply shortfalls. Because no single technology can meet all these needs, storage RD&D naturally spans multiple approaches rather than converging on one solution.
Lastly, current storage technologies face a distinctive degradation problem. Unlike generation assets, storage systems, especially batteries, degrade with every charge–discharge cycle and even when they are not in use, requiring continuous RD&D to manage performance loss, safety risks, and lifespan reduction. These challenges are further amplified in India, where temperatures frequently exceed 40°C. For instance, a lithium-ion battery stored for one year at 40°C will drop to 65% of its full capacity even when stored and left unused.
These differences are not merely technical; they shape how storage RD&D is structured and funded. Public portfolios inevitably reflect choices about which system needs are prioritised and which technologies are considered ready for scale. Examining India’s public storage RD&D portfolio, therefore, offers insight into how the country is balancing near-term deployment needs with longer-term system transformation.
What India’s storage RD&D portfolio signals
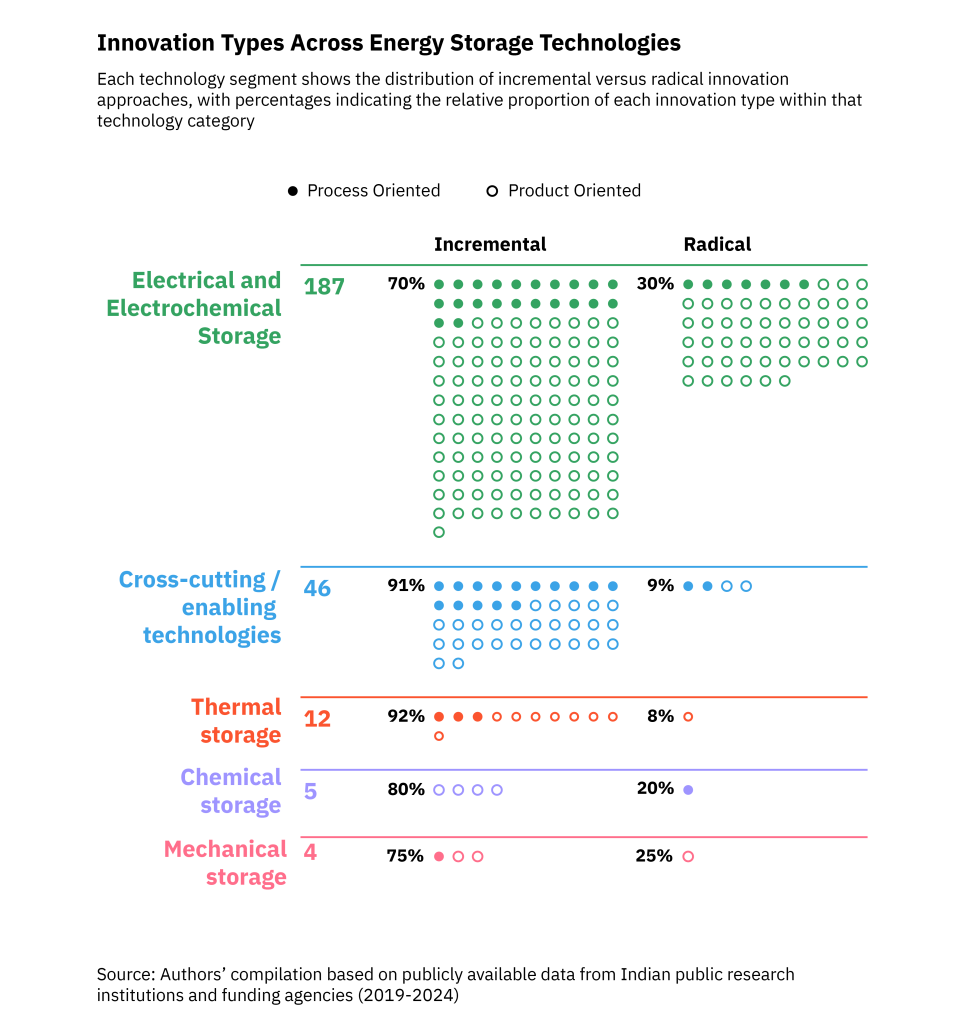
Our review of India’s public energy storage RD&D portfolio reveals a highly concentrated innovation strategy, centred overwhelmingly on electrochemical batteries and shaped by near-term system needs and industrial priorities. Our analysis focuses on publicly funded energy storage RD&D, given its central role in shaping technology trajectories, early-stage research, risk-sharing, and capability-building in India. At the same time, private firms are increasingly active with a growing start-up landscape emerging across the battery energy storage systems (BESS) value chain, from alternative chemistries and battery pack manufacturing to battery management systems (BMS) and battery-as-a-service models, signalling growing private-sector innovation alongside deployment.
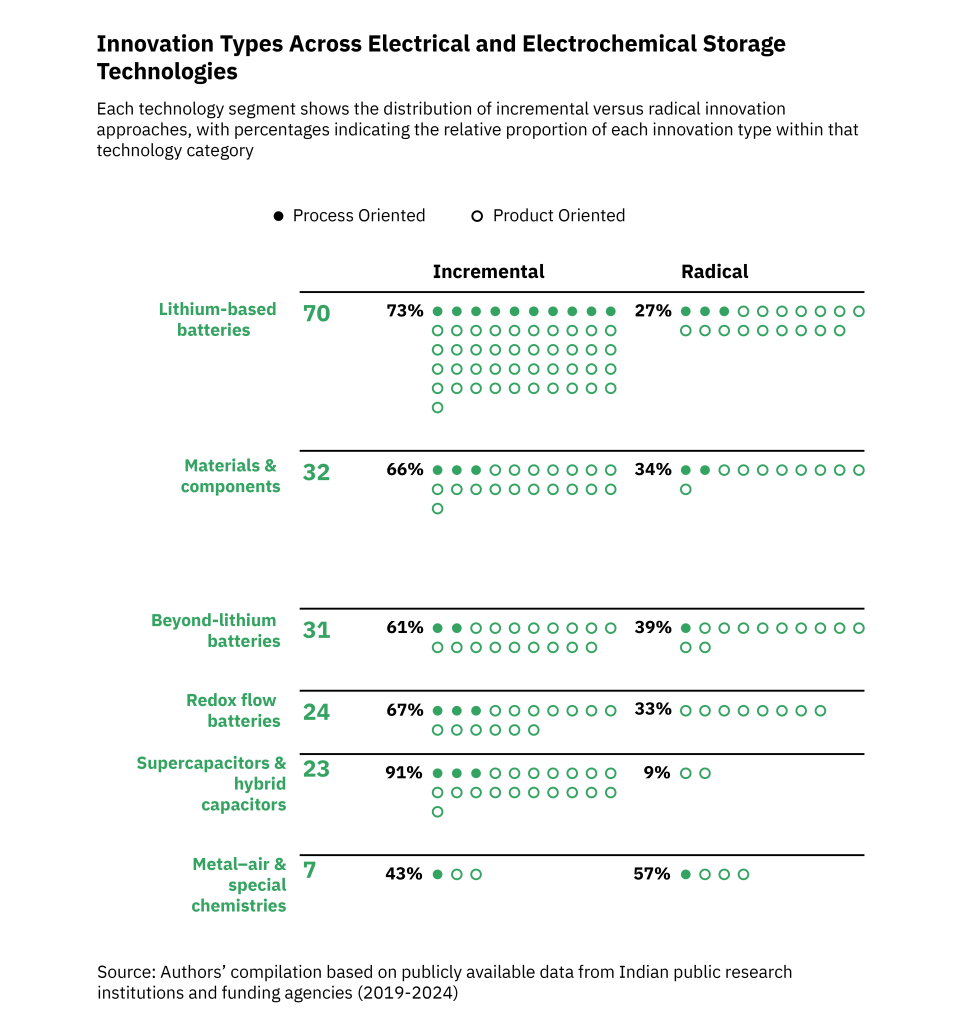
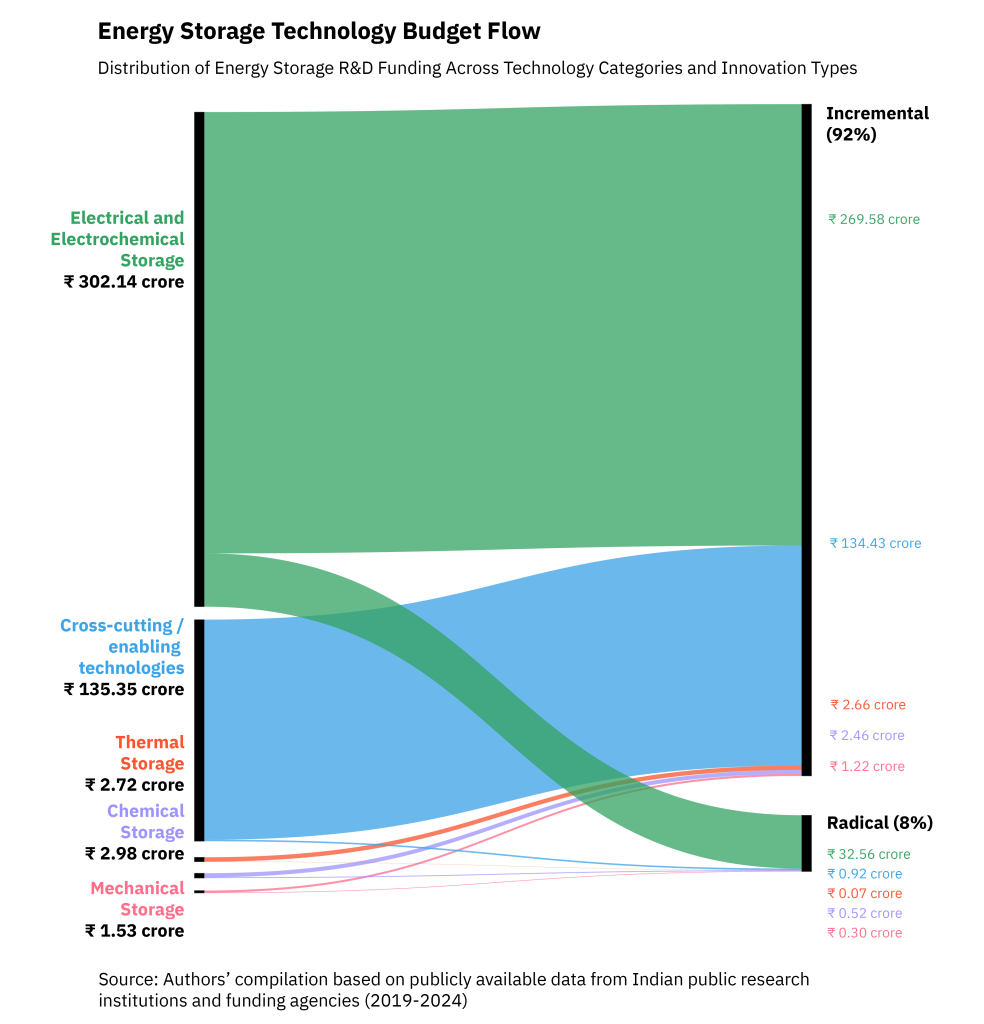
Across the portfolio of over 250 projects, electrochemical and electrical account for more than four-fifths5, with lithium-ion technologies forming the core. These projects focus primarily on incremental improvements to electrode materials, electrolytes, thermal stability, and cycle life, which influence performance, safety, and manufacturability. This emphasis reflects the dual role batteries play in India’s transition: they are both critical to electric mobility and as the most immediately deployable option for short-duration grid storage. While electric mobility and stationary storage batteries differ in performance requirements and, in some cases, chemistry choices, there are important areas of industrial overlap. Cell manufacturing, materials processing, pack assembly, battery management systems, and power electronics form a shared capability base. As India scales up advanced chemistry cell (ACC) manufacturing to meet demand across mobility and power sectors, learning effects and industrial spill-overs are likely to shape innovation trajectories in both domains.
While lithium-ion clearly dominates the portfolio, a smaller but visible set of projects explores alternative chemistries, including sodium- and aluminium-based systems grouped under the beyond-lithium battery category6 in the visual above, as well as redox flow batteries7. Their presence indicates growing awareness of geopolitical and mineral constraints, cost pressures associated with lithium-based systems, and of leveraging India’s relative advantage in sodium availability. Efforts are aimed towards reducing costs, improving efficiency, and developing India-centric designs. However, research into these technologies largely mirrors lithium-ion research in its orientation, focusing on device- and component-level innovation such as materials synthesis and performance benchmarking, rather than being embedded in a broader strategy for long-duration or grid-specific storage applications.
Public institutions such as Indian Institutes of Technology (IITs), Indian Institute of Science (IISc), Bengaluru, Central Electrochemical Research Institute (CECRI), and International Advanced Research Centre for Powder Metallurgy and New Materials (ARCI) are active across battery-focused research areas, alongside DST-supported projects on alternative chemistries and materials.
Beyond batteries, the portfolio thins out rapidly. Thermal energy storage8 appears in a small but meaningful subset of projects, suggesting some engagement with non-battery storage pathways. Yet these projects remain largely disconnected from discussions around industrial heat, renewable integration, and system flexibility, and are treated as standalone research topics.
More striking, however, is the near-absence of long-duration storage technologies. Project-level engagement with pumped hydro9 innovation, compressed air energy storage10, or gravity-based systems11 is minimal. This is notable given India’s significant pumped hydro potential of 176 GW and emerging concerns around grid inertia as solar penetration increases. This pattern does not necessarily imply that long-duration storage is unimportant. Rather, many of these technologies are highly site-specific and infrastructure-intensive, with feasibility shaped more by geography, land and water availability, permitting, and system planning than by laboratory-scale or component-level innovation. As a result, these technologies tend to be approached primarily as planning and project development challenges, rather than as domains where sustained public RD&D is viewed as the binding constraint.
Is India’s battery-first approach to storage a problem?
This focus on batteries raises a familiar question we have explored in earlier blogs on solar energy and green hydrogen in this series: Does India risk narrowing its innovation options by focusing so heavily on batteries? Or is this emphasis a rational response to India’s needs and global technology trajectories?
India’s battery-centric approach is not an outlier. Globally, BESS accounts for the overwhelming majority of new storage deployments and RD&D investment through 2030. In 2025, global investment in batteries for power sector storage is projected to have exceeded USD 66 billion with total installed battery storage capacity reaching 258 GW. Meeting the 2030 goal of tripling renewable energy will require a six-fold expansion of energy storage worldwide, with batteries expected to account for nearly 90% of new capacity additions and other technologies providing supplementary support. Such rapid scaling is largely enabled by declining battery costs. Utility-scale battery storage costs in 2024 fell to about USD 192/kWh, a roughly 93% decline since 2010, making batteries the most competitive option for short- to medium-duration storage.
Even in countries actively funding long-duration energy storage research, batteries continue to dominate near-term deployment because they are modular, quick to deploy, and compatible with existing grid architectures. China illustrates this pattern, combining large investments in pumped hydro with a near fourfold expansion in battery storage capacity in recent years. Similarly, Australia has rapidly expanded BESS but is investing heavily in non-battery storage in parallel, most notably through large pumped hydro projects designed to deliver long-duration energy shifting and system adequacy.
India’s energy storage RD&D strategy can therefore be seen as reflecting a near-term pragmatic reading of current system needs, global cost curves, and institutional constraints rather than a judgment about the technologies that will matter over the full course of the energy transition. By focusing on batteries, India is prioritising technologies that are commercially viable in the short-term, aligned with EV demand, and capable of scaling quickly to support renewable integration.
The question, therefore, is not whether India should shift away from batteries today but whether its storage innovation ecosystem retains the capacity to adapt as system needs evolve. Given current system conditions, rapid renewable scale-up, and the need for short- to medium-duration balancing, batteries remain the most practical and scalable storage option. The challenge for storage RD&D is not about correcting a misallocation in the present, but about ensuring that alternative pathways are not unintentionally side-lined as the power system becomes more complex beyond the early 2030s. In that sense, storage innovation is less about choosing a single winner and more about maintaining a portfolio that can respond to changing technical, economic, and system realities.
This blog is part of our Clean Energy RD&D Insights series, examining India’s evolving clean energy innovation landscape. Read the other blogs on green hydrogen here and solar energy here.We would also like to thank Kunal Agnihotri for his help in designing the visuals for this piece.
Endnotes
Electrochemical energy storage systems store and release electricity through reversible chemical reactions within battery cells (e.g., lithium-ion, sodium-ion, redox flow) ↩︎
Mechanical storage systems convert electrical energy into mechanical potential or kinetic energy (e.g., pumped hydro, compressed air, flywheels, gravity systems) ↩︎
Thermal energy storage systems store energy as heat or cold in a medium (e.g., molten salts, water, phase-change materials) for later use in power generation or direct thermal applications ↩︎
Chemical storage systems convert electricity into chemical energy carriers (e.g., hydrogen, synthetic fuels, ammonia) through processes such as electrolysis ↩︎
In this analysis, electrical and electrochemical storage technologies are grouped together because they share similar innovation characteristics and RD&D pathways. Both rely on advances in materials science, power electronics, and system integration, and are typically deployed for short- to medium-duration applications requiring fast response times. In India’s public RD&D portfolio, these technologies are also funded, evaluated, and implemented through similar institutional and programmatic channels, making it analytically meaningful to examine them together ↩︎
Beyond-lithium batteries category includes multiple chemistries such as sodium- and aluminium-based systems. These are grouped together as they represent alternative chemistries within broadly similar battery architectures. These technologies often target the same applications as lithium-ion systems, draw on comparable manufacturing processes, and face similar RD&D challenges related to materials performance, cost reduction, and scalability. Redox flow batteries and metal–air systems are treated as separate categories because they differ more fundamentally in design, operating principles, and innovation pathways ↩︎
Besides lithium-ion batteries, flow batteries could emerge as a breakthrough technology for stationary storage as they do not show performance degradation for 25-30 years and are capable of being sized according to energy storage needs with limited investment ↩︎
Thermal Energy Storage captures and stores heat or cold in a medium (like water, rock, or salt) for later use, balancing energy supply and demand ↩︎
Pumped storage hydropower a large-scale energy storage method that uses two reservoirs at different elevations to act like a giant rechargeable battery, storing surplus electricity by pumping water uphill and releasing it downhill through turbines to generate power when needed ↩︎
Compressed Air Energy Storage stores excess electricity by compressing air and storing it in underground caverns or tanks, releasing it later to drive turbines and generate power, effectively acting like a large battery ↩︎
Gravity-based energy storage systems store excess electricity by lifting heavy masses (like concrete blocks or water) and release it by allowing them to fall, converting potential energy back into power using a generator, acting as a sustainable, long-lasting alternative to batteries ↩︎